
Former Rakeedhoo Council SG Unlawfully Drew Two Salaries, Audit Reveals
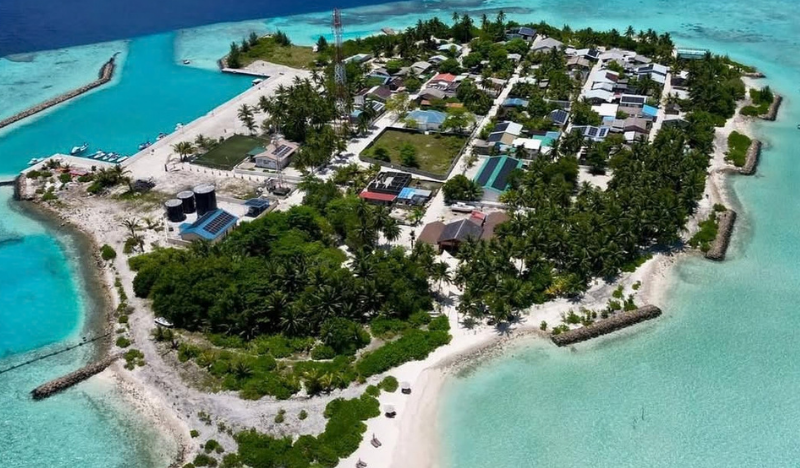
Rakeedhoo / Photo: Social Media
The former temporary Secretary-General (SG) of the Vaavu Rakeedhoo Council unlawfully drew two salaries over a four-year period, pocketing MVR 337,600 in extra payments under the label of “Mosque Wage,” according to a report by the Auditor General’s Office.
According to the report, the employee received the additional payments despite already drawing a salary as the council’s temporary Secretary-General. Auditors said the arrangement breached state financial regulations.
The payments were deposited monthly into the employee’s personal bank account based on a document attached to the council’s banking instructions. The document had been signed and authorised by the council president, vice-president, another council employee and the Secretary-General, according to the report.
According to the audit, a total of MVR 337,600 was recorded as “Mosque Wage” over a four-year period. The disbursements began in 2022 with MVR 88,200, followed by MVR 69,300 in 2023 and MVR 61,300 in 2024, before rising significantly to MVR 118,800 in 2025.
The Audit Office said the council had no records showing the number of days worked, how the payments were calculated or what work had been performed in return for the money.
Auditors also noted that the council already employed a Council Assistant responsible for mosque-related duties during the period in question.
The audit also identified MVR 79,771 in payments categorized as “other payments” deposited directly into the former temporary Secretary-General’s personal bank account.
These transfers comprised MVR 6,890 in 2022, MVR 5,200 in 2023, MVR 25,881 in 2024, and MVR 41,800 in 2025.
Although these funds were purportedly intended for third-party vendors or individuals owed money by the council, auditors found no invoices, supporting records, or documentation identifying the intended payees or confirming that the rightful recipients ever received the money.
The Audit Office recommended verifying how the money deposited into the employee’s personal account was ultimately used and taking steps to recover any funds that cannot be accounted for.
It also recommended referring the matter concerning the alleged receipt of two salaries to the Anti-Corruption Commission (ACC) for investigation and pursuing recovery of any state funds found to have been lost.
The audit identified other financial management issues at the council.
The report said pension contributions deducted from employees’ salaries had not been transferred to the Pension Office. Council records showed that MVR 149,410 was due to the Pension Office in 2024, but no payments were made during that year.
Auditors also found that officials responsible for overseeing the council’s finances had failed to ensure that accounting records and transaction documents were properly prepared and maintained.
The council was further found not to have maintained a fixed asset register in accordance with state financial regulations.
In another finding, revenue collected by the council was routinely deposited into an employee’s personal bank account before being transferred to the council’s official account. The report said MVR 11,670 was transferred to the council’s account under this arrangement in 2022, but the council could not provide supporting documentation for the transactions.