
High Court Rules Tree Top Hospital Contractor Turkmax Must Pay MVR 25 Million in Taxes
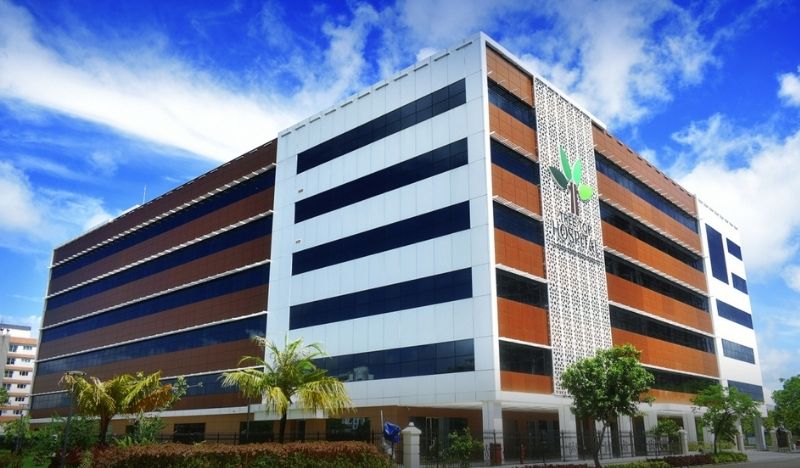
The High Court has upheld a determination by the Maldives Inland Revenue Authority (MIRA) requiring Turkish contractor Turkmax, the firm that constructed Tree Top Hospital, to pay MVR 25 million in Goods and Services Tax (GST) on imported materials.
The High Court delivered the judgment after Turkmax appealed against an earlier ruling by the Tax Appeal Tribunal that supported MIRA’s tax assessment.
advertisement
advertisement
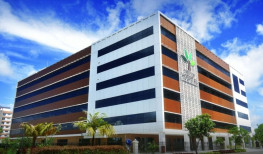
The dispute stems from a contract between Tree Top Health and Turkmax to construct Tree Top Hospital in Hulhumalé, an infrastructure project valued at USD 110 million.
Following an audit of the GST returns filed by Turkmax for the project, MIRA determined that the contractor was liable to pay an additional MVR 25 million in GST on core materials imported for the hospital’s construction.
Turkmax initially challenged MIRA’s decision before the Tax Appeal Tribunal, contending the assessment was flawed. The company argued that the materials had been imported by Tree Top itself, asserting that although the initial written contract stipulated Turkmax would import the goods, the parties had subsequently agreed verbally to alter this arrangement.
However, the Tribunal affirmed MIRA’s assessment.
Appealing the decision to the High Court, Turkmax claimed the tax audit was conducted unfairly and that MIRA had failed to seek relevant documentation directly from Tree Top. The contractor further argued that the Tribunal erred in rejecting new evidence submitted during the tribunal proceedings.
In its judgment, the High Court held that MIRA had provided Turkmax with sufficient time and opportunity to respond during the audit process.
The court noted that MIRA is under no statutory obligation to procure documentation from third parties, stating that the burden of proof rests on the taxpayer when seeking deductions or exemptions.
The High Court further observed that no written amendments had been executed to modify the original contract between Tree Top and Turkmax, ruling that a taxpayer cannot evade statutory tax liabilities based on unilateral interpretations or purported oral agreements. The judges also affirmed that the Tribunal did not err in refusing to admit evidence that had not been submitted during the initial audit stage.
Concluding that there were no legal grounds to overturn the Tax Appeal Tribunal’s decision, a three-judge panel of the High Court unanimously upheld the tribunal’s ruling.